
Financial Planning: 7 Steps to Create a Financial Plan in the UK
Financial planning is the process of organising your income, spending, savings, debts, investments, pensions, taxes and financial protection around clear financial goals. A financial plan shows your current financial position and sets out the actions required to improve your financial security over time. In the UK, personal financial planning can also involve Individual Savings Accounts (ISAs), pensions, tax allowances, insurance, mortgages and estate planning.
The right approach depends on your income, expenses, assets, debts, family circumstances, risk tolerance and financial objectives. Financial planning is not only for wealthy individuals. It can help anyone manage cash flow, build emergency savings, reduce debt, prepare for retirement and make more structured financial decisions.
This guide explains what financial planning is, the 7 steps of financial planning, what a financial plan should include, how much you should save and when professional financial advice may be appropriate. This guide provides general information and does not constitute personalised investment, pension or regulated financial advice.
What Is Financial Planning?
Financial planning is the process of assessing your current finances, setting measurable goals and creating a structured strategy for managing money over time. A financial plan considers your overall financial position rather than focusing on a single investment, tax decision or financial product. It can cover:
- income
- household expenses
- savings
- debts
- assets
- investments
- pensions
- insurance
- tax
- mortgages
- estate planning
- short-term goals
- long-term goals
For example, someone may want to build an emergency fund, clear expensive debt, save towards a home deposit, increase pension contributions and invest for longer-term goals. Each decision can affect the others. Financial planning brings these areas together within one financial roadmap and helps establish which goals should receive priority.
Why Is Financial Planning Important?
Financial planning is important because it gives your financial decisions structure, direction, and measurable objectives. Without a clear plan, saving, borrowing, investing, and spending decisions can become disconnected. For example, someone could invest significant amounts each month while carrying expensive short-term debt or having no accessible emergency savings. Financial planning helps you understand what your money needs to achieve before deciding how it should be allocated.
What Are the Benefits of Financial Planning?
Financial planning can improve cash-flow control, financial resilience, goal setting and long-term decision-making. A structured financial plan can help you understand your income and spending, establish a realistic household budget, build emergency savings, reduce expensive debt and prepare for major purchases. It can also help you organise pension contributions, define investment objectives, use relevant tax allowances and identify financial protection needs.
Longer-term planning can support retirement, family protection, estate planning and wealth-transfer objectives. A written financial plan also creates a benchmark for measuring progress. Instead of judging your finances only by your current bank balance, you can compare your savings, debt, investments and pension position with defined financial targets.
What Are the 7 Steps of Financial Planning?
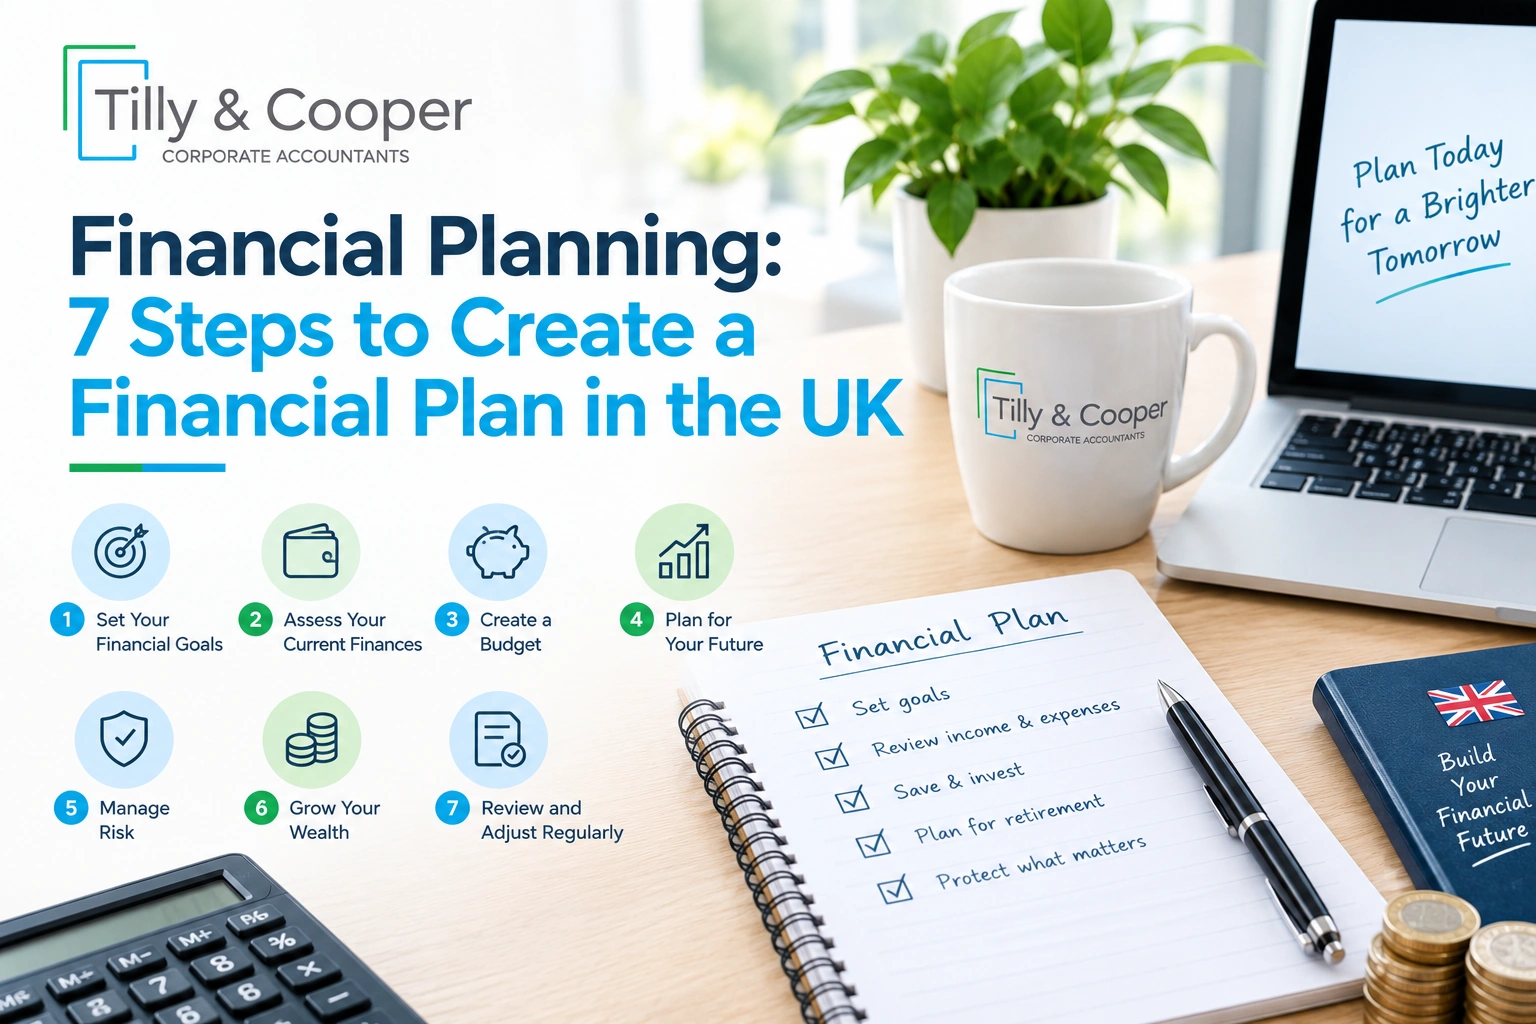
A practical financial planning process can be divided into 7 steps: assessing your finances, setting goals, identifying gaps and risks, prioritising objectives, creating a strategy, implementing the plan and reviewing it regularly.The process moves from understanding your current position to deciding where you want to go and how your available financial resources can support those objectives.
1. Assess Your Current Financial Position
Start by establishing what you own, what you owe, what you earn, and what you spend. Record your:
- monthly income
- essential expenses
- discretionary spending
- savings
- investments
- pension balances
- property
- other assets
- mortgages
- personal loans
- credit cards
- other liabilities
You can use this information to calculate your net worth:
Net worth = Total assets − Total liabilities
For example, someone with £250,000 of assets and £150,000 of liabilities has a net worth of £100,000. Net worth provides a useful financial snapshot, but it should not be considered in isolation. Cash flow also matters because someone can own substantial assets while struggling to meet regular household expenses.
2. Set Clear Financial Goals
Set specific financial goals with measurable amounts and realistic target dates wherever possible. Financial goals can be divided according to timeframe. Short-term goals may include building emergency savings, clearing credit-card debt, or creating a monthly spending budget.
Medium-term goals could include buying a home, starting a business, changing careers, or funding education. Long-term goals often include retirement, financial independence, mortgage repayment, investment growth and estate planning. A useful method is to create SMART financial goals. SMART stands for:
- Specific
- Measurable
- Achievable
- Relevant
- Time-bound
For example:
“I will build a £6,000 emergency fund within 12 months by saving £500 each month.”This is more useful than saying, “I want to save more money.” The goal identifies the amount, purpose, monthly contribution, and target date. This makes progress easier to measure and connects the financial objective with a specific action.
3. Identify Financial Gaps and Risks
Compare your current position with your financial goals to identify what could prevent you from achieving them. Financial gaps can include:
- insufficient monthly savings
- high-interest debt
- inadequate emergency funds
- low pension contributions
- excessive investment concentration
- insufficient insurance protection
- poor cash-flow management
- unrealistic retirement assumptions
You should also consider financial risks such as loss of income, illness, death, inflation, unexpected household expenses and investment losses. Identifying a risk does not eliminate it. It allows you to decide whether the risk should be reduced, insured against, funded through savings or otherwise managed.
4. Prioritise Your Financial Goals
Rank your financial goals according to their urgency, cost, risk and timeframe. Not every objective can be funded at the same time. For example, establishing essential emergency savings and dealing with expensive short-term borrowing may take priority over increasing higher-risk investments. Timeframe is particularly important.
Money required for a house deposit in 2 years normally requires a different approach from retirement savings that may not be needed for 30 years. Your financial priorities should therefore reflect your personal circumstances rather than a universal formula.
5. Create Your Financial Strategy
Decide how much money you can allocate to each priority and which financial actions will support your goals. Your strategy may include:
- creating a household budget
- automating monthly savings
- repaying expensive debt
- building an emergency fund
- increasing pension contributions
- using appropriate tax-efficient accounts
- defining investment objectives
- reviewing financial protection
- managing mortgage repayments
- updating estate-planning arrangements
Each action should connect directly to a financial objective. For example, saving £500 every month is not a complete strategy unless you know whether that money is intended for emergency savings, a home deposit, retirement or another goal.
6. Put Your Financial Plan Into Action
A financial plan becomes useful when the agreed financial actions are implemented. Implementation may involve opening separate savings accounts, setting standing orders after payday, increasing pension contributions, changing debt repayments, reviewing insurance arrangements or organising investment accounts.
You may also need to prepare or update legal documents such as a will or Lasting Power of Attorney. Where an action involves a personalised recommendation about regulated investments, pensions, mortgages or insurance products, consider whether appropriately regulated professional advice is required.
7. Review and Update Your Financial Plan
Review your financial plan regularly to ensure your goals, assumptions and financial strategies remain appropriate. Income, spending, family circumstances, tax rules, investment values and financial priorities can change. A structured annual review can help determine whether you remain on track. You should also review the plan after significant events such as:
- marriage
- divorce
- having a child
- buying a property
- changing employment
- starting a business
- receiving an inheritance
- significant income changes
- approaching retirement
- the death of a partner or dependant
A review does not mean redesigning the entire financial plan every year. Its purpose is to identify material changes that require action.
What Are the Main Components of a Financial Plan?
The main components of a financial plan include cash flow, emergency savings, debt management, financial protection, investments, pensions, tax and estate planning. Not every person will need the same level of planning in every area. The components should reflect your financial circumstances and objectives.
Cash Flow and Budgeting
Cash-flow planning compares the money entering your household with the money leaving it. Start with your regular net income and identify spending on housing, utilities, food, transport, childcare, insurance, debt repayments, subscriptions and discretionary purchases. You should also record amounts allocated towards savings, pensions and investments.
A budget should do more than record historical spending. It should determine how available income will be allocated between current expenses and future goals. Regular cash-flow reviews can show whether your current lifestyle leaves enough capacity to fund your financial objectives.
Emergency Savings
An emergency fund provides accessible money for essential unexpected expenses or a temporary reduction in income. MoneyHelper describes 3 to 6 months of essential outgoings as a useful rule of thumb for an emergency savings cushion. For example, someone with essential household expenditure of £2,000 per month could use £6,000 to £12,000 as a starting range. The appropriate emergency fund depends on factors such as:
- employment security
- number of household income sources
- dependants
- essential monthly costs
- existing debt
- insurance protection
- access to other cash
Emergency savings should normally be readily accessible. Money required at short notice should not depend entirely on selling investments because their value may have fallen when the money is needed.
Debt Management
Debt planning identifies what you owe, what each debt costs and which liabilities should receive priority. For each debt, record the outstanding balance, interest rate, minimum payment and repayment terms. Expensive borrowing can significantly reduce the amount available for savings, pensions and other financial goals.
However, not every debt should automatically be repaid immediately. Your emergency fund, mortgage terms, interest rates, early repayment charges and other financial priorities should also be considered.
Financial Protection and Insurance
Financial protection planning considers how your household would cope financially with events such as illness, disability, loss of earnings or death. Relevant protection can include:
- life insurance
- income protection
- critical illness cover
- buildings insurance
- contents insurance
The appropriate level of protection depends on your family, debts, income, employer benefits and available savings. Someone supporting children and repaying a large mortgage may have very different protection needs from someone with no dependants and substantial accessible assets.
Investment Planning
Investment planning involves allocating money towards longer-term objectives while considering risk, timeframe, access requirements and potential returns. An investment strategy should consider:
- financial objective
- investment timeframe
- risk tolerance
- capacity for loss
- diversification
- investment charges
- tax treatment
- access requirements
Diversification can reduce concentration risk by spreading exposure across different investments or asset classes. It does not eliminate investment risk or guarantee positive returns. Money required for short-term commitments should generally be considered separately from long-term investment capital.
Retirement and Pension Planning
Retirement planning estimates the income and assets you may need after reducing or stopping work and considers how those resources will be built. A retirement plan should consider your expected retirement age, desired income, workplace and personal pensions, State Pension expectations, existing savings and investments, housing costs, future living expenses, inflation and other income sources.
For the 2026/27 tax year, the standard pension annual allowance is £60,000. However, a lower allowance can apply to some high-income individuals and people who have flexibly accessed defined contribution pensions. The £60,000 allowance is not a recommended contribution level. Pension contributions, tax relief and annual allowance calculations depend on individual circumstances.
Tax Planning
Tax planning considers how legitimate tax allowances and tax-efficient arrangements can support your wider financial goals.
UK personal financial planning may involve:
- ISAs
- pension tax relief
- Personal Allowance
- dividend taxation
- Capital Gains Tax
- taxation of savings
- inheritance and estate considerations
For 2026/27, the overall ISA subscription limit is £20,000. Interest, income and capital gains generated within qualifying ISAs are generally sheltered from UK tax.
From 6 April 2027, the Cash ISA subscription limit is scheduled to become £12,000 for people under 65, while the overall ISA limit remains £20,000. People aged 65 and over will retain a £20,000 Cash ISA limit under the announced rules.
For 2026/27, the Dividend Allowance is £500 and the Capital Gains Tax annual exempt amount for most individuals is £3,000.
Tax allowances can change between tax years.
A financial decision should also not be made solely because it produces a tax advantage. The underlying financial objective, costs and risks remain important.
Estate Planning
Estate planning organises how your assets and financial affairs should be managed during your lifetime and transferred after death. Depending on your circumstances, estate planning can involve:
- a valid will
- Lasting Powers of Attorney
- beneficiary nominations
- trusts
- property ownership
- business succession
- lifetime gifts
- inheritance planning
- legacy objectives
Estate planning is not only relevant to wealthy families. Anyone who owns a property, investments, a business or other significant assets may benefit from keeping their legal documents and beneficiary arrangements under review. Complex estate-planning decisions may require legal and tax advice.
How Much Should You Save Each Month?
The amount you should save each month depends on your income, essential expenses, existing debts and financial goals rather than one universal savings percentage. A useful starting calculation is:
Monthly income − essential expenses − debt commitments = available financial capacity
You can then allocate the available amount between priorities such as:
- emergency savings
- short-term goals
- pension contributions
- investments
- debt reduction
- other financial objectives
For example, someone with £4,000 of monthly net income, £2,500 of essential costs and £500 of debt commitments has £1,000 remaining before discretionary spending and additional financial goals. That does not automatically mean the full £1,000 should be invested or saved.
The appropriate allocation depends on the person’s circumstances.nIf your target feels unaffordable, start with a sustainable amount and increase it when your financial position improves. Automating savings shortly after payday can also make planned saving more consistent.
When Should You Start Retirement Planning?
You should generally start retirement planning as early as practical because a longer timeframe gives contributions and investment returns more time to accumulate. Someone beginning in their twenties has a longer period to build retirement assets than someone beginning in their forties. However, starting later does not make retirement planning pointless. It may simply require different contribution levels, objectives or retirement assumptions.
A retirement review should consider your current pension value, future contributions, employer contributions, expected retirement age, desired retirement spending, State Pension expectations, housing costs, inflation and other savings or investments. Rather than relying on one generic retirement target, estimate the income your expected lifestyle could require and compare it with the resources you are currently building.
Can You Create a Financial Plan Yourself?
Yes. You can create a financial plan yourself where your circumstances are relatively straightforward and you understand the financial decisions involved.
A basic personal financial plan can begin with:
- calculating your net worth
- reviewing monthly income and expenses
- listing debts and interest rates
- creating an emergency fund target
- setting measurable financial goals
- reviewing pension contributions
- defining investment objectives
- identifying financial protection needs
- checking relevant tax allowances
- reviewing the plan annually
You do not normally need personalised regulated financial advice simply to establish a household budget, record your assets and liabilities or create a savings target. Professional support becomes more relevant as the financial consequences, technical complexity or regulatory requirements of a decision increase.
When Should You Get Professional Help With Financial Planning?
Professional help can be useful when your financial affairs become complex or when you need personalised advice about regulated financial products. Different professionals can provide different types of support, so it is important to understand what service is actually being offered.
What Does a Financial Planner Do?
A financial planner can help organise your current financial position, future objectives and financial strategies into a structured plan. Depending on their qualifications, services and regulatory permissions, their work may include reviewing cash flow, setting goals, considering debt-management strategies, planning for retirement, assessing financial protection needs and monitoring progress.
They may also help identify areas requiring specialist tax, investment, pension or estate-planning advice. However, creating a broad financial plan and giving personalised regulated financial-product advice are not automatically the same activity.
What Is the Difference Between a Financial Planner and a Financial Adviser?
A financial planner generally focuses on the wider financial strategy, while a financial adviser may provide personalised recommendations about regulated financial products where appropriately authorised. The terms can overlap, and some professionals provide both services.
| Financial Planner | Financial Adviser |
| May create a broad financial roadmap | May provide personalised financial recommendations |
| Often focuses on goals and strategy | May recommend regulated financial products |
| May review cash flow and long-term priorities | May advise on areas such as investments or pensions |
| Can monitor progress towards goals | Can provide one-off or ongoing regulated advice |
| Service depends on qualifications and scope | Advice depends on regulatory permissions |
Job titles alone should therefore not determine which professional you choose.
The FCA states that almost all UK firms providing financial services must be appropriately authorised or registered and that consumers can use its Firm Checker to confirm whether a firm is authorised and has permission to provide the required service.
When Should You Consider Regulated Financial Advice?
Regulated financial advice can be useful when you need a personalised recommendation about investments, pensions or another regulated financial product.
You may consider professional advice where you:
- have substantial investments
- have several pension arrangements
- are approaching retirement
- need advice about pension withdrawals
- receive a significant inheritance
- need personalised investment recommendations
- have complex protection requirements
- own several properties
- own a business
- need business succession planning
- face complex financial or tax decisions
MoneyHelper explains that regulated financial advisers can provide personalised recommendations based on an individual’s situation and financial goals. Before accepting regulated financial advice, check the firm’s FCA status and confirm that it has permission for the specific services you need.
What Are the Most Common Financial Planning Mistakes?
Common financial planning mistakes include setting vague goals, ignoring cash flow, carrying expensive debt, taking unsuitable investment risk, and failing to review the plan.
Setting Vague Financial Goals
A goal such as “I want to become financially secure” is difficult to measure. Define the amount, objective and timeframe wherever possible.
Ignoring Cash Flow
Long-term investment planning cannot correct a household budget that consistently spends more than it receives. Understand your monthly cash flow before committing substantial amounts to longer-term objectives.
Having No Emergency Fund
Unexpected expenses can force you to use credit or sell investments when you do not have accessible cash available. Build an emergency reserve that reflects your essential expenses and financial circumstances.
Ignoring Expensive Debt
High-interest borrowing can absorb money that could otherwise support savings, pensions or other financial goals. Review interest rates and repayment terms when establishing priorities.
Investing Without Considering Timeframe
An investment may fall in value shortly before the money is needed. Match your financial strategy to the expected date of the financial goal.
Taking Too Much Concentration Risk
Holding a large proportion of your wealth in one company, sector, property or other asset can create concentration risk. Diversification can spread exposure, although it cannot eliminate investment losses.
Ignoring Tax
Tax can affect investment returns, pensions, property decisions and wealth transfers. Consider the tax consequences of major financial decisions while keeping the underlying financial objective in focus.
Failing to Review the Plan
A financial plan can become outdated when your income, family circumstances, tax position or goals change. Regular reviews help identify assumptions that no longer reflect your circumstances.
How Often Should You Review Your Financial Plan?
Review your financial plan at least once a year and after significant financial or personal changes. An annual review can compare your actual results with the targets established in the previous plan. Consider changes to:
- income
- expenses
- net worth
- emergency savings
- debts
- pension contributions
- investments
- insurance
- tax position
- financial goals
You should also reconsider assumptions about retirement, inflation, future expenditure and investment risk. A financial plan is therefore an ongoing process rather than a document prepared once and forgotten.
How Can Tilly & Cooper Help With the Tax Side of Financial Planning?
Tilly & Cooper can help individuals understand the tax and accounting matters that interact with their wider financial plans. Financial decisions can have different tax consequences depending on the type of income, investment, asset, pension contribution, or transaction involved.
Relevant areas can include:
- Income Tax
- taxation of savings
- dividend income
- Capital Gains Tax
- pension tax considerations
- property income
- investment taxation
- personal tax returns
- business income
- estate and inheritance tax considerations
Tax planning should form part of a wider financial strategy rather than being considered only after a financial transaction has taken place.Where personalised recommendations about investments, pensions or other regulated financial products are required, those services should be obtained from a professional or firm with the appropriate FCA authorisation and permissions. The objective of a strong financial plan is clear: understand your current financial position, define measurable goals, allocate your resources effectively, manage financial risks and review your progress as your circumstances change.
Need help with the tax side of your financial plan? Tilly & Cooper can help you understand how Income Tax, Capital Gains Tax, pensions, investments, property income and estate matters may affect your wider financial position.