
UK Tax Residency Certificate: HMRC Application and Eligibility Guide
A UK tax residency certificate, officially called a Certificate of Residence (CoR), is issued by HM Revenue & Customs (HMRC) to confirm UK tax residence for a specified date or period. An eligible taxpayer uses it to support a claim under a Double Taxation Agreement (DTA) when receiving income from another country.
Being UK tax resident is not the same as qualifying for every treaty benefit. The applicant must satisfy the relevant treaty conditions, and the overseas tax authority determines whether reduced withholding tax or a refund is available. A CoR provides residence evidence; it does not itself award tax relief.
What Should You Know Before Applying?
Before applying for a UK Tax Residency Certificate, you must establish your UK tax residence, identify the relevant Double Taxation Agreement (DTA), and confirm why the overseas authority requires the certificate. HMRC uses this information to assess whether it can issue a Certificate of Residence (CoR) for the requested period.
| Question | Direct answer |
| Who issues a UK Certificate of Residence? | HMRC. |
| Can an individual or limited company apply? | Yes, subject to the relevant residence and treaty conditions. |
| Does a UK address alone prove treaty residence? | No. |
| Is a tax treaty needed? | For a treaty-based CoR, yes. HMRC may issue a residence confirmation letter for another purpose. |
| Can an accountant apply? | Yes, with appropriate authority; separate consent may be needed for HMRC to send the document to the agent. |
| Can HMRC certify a future period? | Not through the ordinary CoR procedure. |
| Is there a guaranteed turnaround? | HMRC does not publish a fixed processing time for every case. |
| Does the certificate guarantee relief abroad? | No. The overseas authority applies its treaty and domestic procedures. |
The principal application sequence is residence assessment → treaty entitlement → HMRC evidence → overseas relief claim.UK tax residence does not automatically establish entitlement to treaty relief. HMRC determines whether it can certify the applicant’s residence, while the overseas tax authority assesses the applicable treaty conditions and decides whether to grant reduced withholding tax or another form of relief.
Who Qualifies for a UK Residence Certificate?
HMRC accepts applications from individuals, sole traders, companies, partnerships, trusts, pension schemes, charities, public bodies and certain investment arrangements. Eligibility to submit a request does not establish entitlement to a treaty benefit.
| Applicant | Residence consideration | Useful identification to prepare |
| Individual | Statutory Residence Test (SRT) | Full name, address, National Insurance number and UTR where applicable |
| Sole trader | Individual’s residence under the SRT | Personal identifiers and Self Assessment details |
| UK limited company | Incorporation and corporate residence rules, including treaty exceptions | Registered name, company number, address and Corporation Tax UTR |
| Overseas-incorporated company | Central management and control and treaty position | Incorporation and management records, UK tax reference |
| Partnership or LLP | Partners’ or members’ residence and relevant treaty wording | Partnership reference, partner names and residence evidence |
| Trust, charity or pension scheme | Rules governing the particular entity | Organisation details and relevant HMRC reference |
HMRC requires the name, address and Unique Taxpayer Reference (UTR) or National Insurance number of the person for whom a certificate or letter is requested, as applicable. The online form may ask for further identification according to the applicant category.
How Does the Statutory Residence Test Apply to Individuals?
The SRT determines an individual’s UK residence for a UK tax year running from 6 April to 5 April. It examines automatic overseas tests, automatic UK tests and, where necessary, sufficient ties to the UK. An individual present in the UK for at least 183 days during the relevant tax year meets an automatic UK residence test.
Spending fewer than 183 days does not automatically mean non-residence: work, accommodation, family and other ties may establish residence under the remaining tests. If an individual has not filed a Self Assessment return for the requested period, HMRC may ask for UK day counts, arrival and departure dates, the reason for residence where presence was below 183 days, and split-year details.
How Do the Residence Rules Apply to Companies?
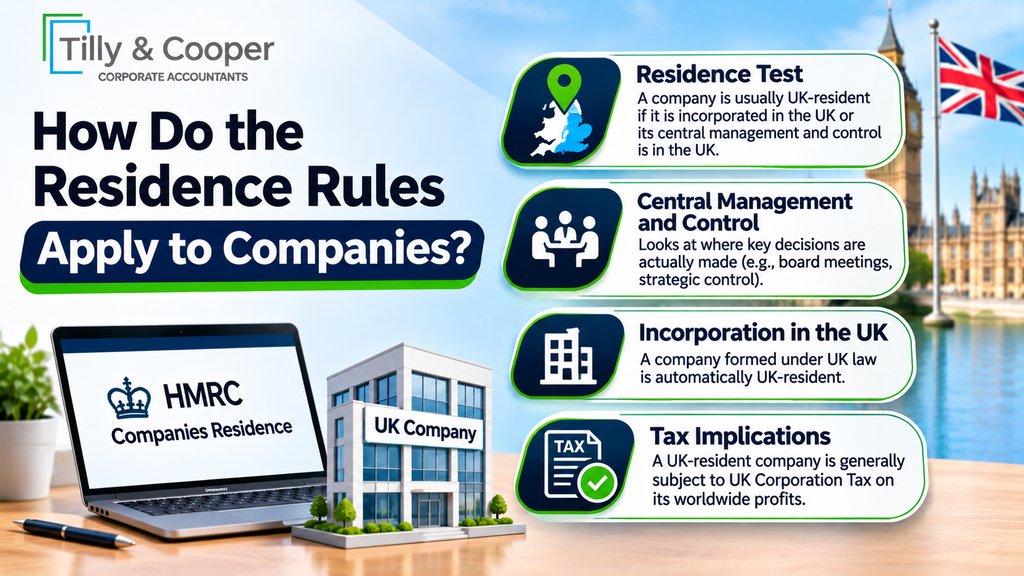
A UK-incorporated company is generally UK tax resident, subject to applicable domestic and treaty exceptions. An overseas-incorporated company may also be UK resident if its central management and control is exercised in the UK. A director’s passport or overseas address alone does not decide corporate residence.
A newly incorporated company without its first Corporation Tax return must give HMRC the names and addresses of its directors and shareholders and explain why it considers itself UK resident. The company may also need management or tax records to support that position.
What Evidence Does HMRC Need for Partnerships and LLPs?
Most UK partnerships and LLPs are tax-transparent and cannot themselves be UK treaty residents under most DTAs. HMRC can instead certify UK residence for qualifying partners or LLP members. A small number of treaties contain exceptions. Where all partners are UK resident, supply a list of every partner’s name and confirm that each is UK resident at the date of the request.
Where some partners are non-UK resident, supply a partnership contact name and address plus a list naming every partner, separating UK-resident from non-resident partners and confirming which partners are UK resident at the date of the request. For a certificate covering a different period, HMRC may also require confirmation of each relevant partner’s residence during that period. Non-UK resident partners do not qualify for UK treaty benefits merely because they belong to a UK partnership.
Which Tax Treaty Conditions Must Be Checked?
A Double Taxation Agreement can reduce source-country tax on qualifying income, but UK residence alone does not establish the right to every rate reduction. Check the country, income article, beneficial ownership requirements and any applicable taxability conditions.
Liable to tax generally describes a person within the UK’s general scope of taxation by reason of residence or a comparable connection. Subject to tax, where required by a treaty article, concerns the treatment of particular income. An allowance reducing actual tax to zero does not necessarily remove that income from the scope of tax; a statutory exemption can produce a different result.
For example, some treaty provisions require foreign dividends to be subject to UK tax. UK company dividend exemptions may therefore affect whether HMRC can issue the requested treaty certificate for that income. The correct answer depends on the specific treaty and statutory rules. A beneficial-ownership requirement may also apply to dividends, interest or royalties. A nominee receiving money for another person may not satisfy it.
What Information Must the HMRC Application Include?
HMRC needs enough information to identify the taxpayer and assess the particular treaty claim.
| Required attribute | Information to include |
| Applicant identity | Legal name, address and appropriate UTR or National Insurance number |
| Overseas jurisdiction | Country requesting residence evidence |
| Treaty and article | Applicable UK DTA and relevant income article |
| Income category | Business profits, dividends, interest, royalties, pension or other income |
| Certification period | Date or period being certified; no future period |
| Purpose | Foreign tax relief or another specific reason for residence confirmation |
| Beneficial ownership | Declaration if required by the treaty |
| UK tax treatment | Confirmation of whether the income is subject to UK tax if required |
| Foreign paperwork | Overseas authority’s prescribed form, when applicable |
Check the current treaty text using the tax treaty collection. The article numbers for dividends, interest and royalties frequently follow the OECD model but can differ by treaty.
How Do You Apply Online or Through an Accountant?
The standard route is HMRC’s Certificate of Residence application service. Applicants who cannot apply online may use the relevant postal address in that guidance.
- Identify the period and basis of UK tax residence.
- Confirm the overseas jurisdiction, treaty and type of income.
- Prepare legal name, address, tax reference and supporting records.
- Complete the HMRC online request and attach any foreign authority form.
- Answer HMRC’s additional questions if it requests clarification.
- Once issued, send the document to the overseas authority or payer under its claim rules.
An authorised tax agent can apply using the relevant HMRC Agent Services Account. However, HMRC may issue the CoR directly to an agent or other third party only when the taxpayer has consented to that disclosure. A valid form 64-8 or another acceptable authorisation may provide consent; include it with the request if HMRC does not already hold it.
The ordinary CoR process does not certify future residence. HMRC has a restricted pre-order facility for qualifying Large Business cases with December accounting-period ends. HMRC does not guarantee a single processing time, so submit applications before overseas relief or repayment deadlines.
Can a Certificate Reduce Foreign Withholding Tax?
A CoR may support a reduction in foreign tax when the overseas authority accepts the evidence and the applicant meets the treaty conditions. Illustrative example only: Assume a UK-resident company receives £10,000 in royalties from a foreign customer. Suppose, hypothetically, the country’s domestic withholding rate is 20% and the applicable treaty rate for an eligible recipient is 5%.
| Calculation | Amount |
| Gross royalties | £10,000 |
| Hypothetical domestic withholding at 20% | £2,000 |
| Hypothetical treaty withholding at 5% | £500 |
| Potential reduction | £1,500 |
These rates are not verified rates for any named country. For a real payment, check current overseas law, the exact treaty, entitlement conditions and the source country’s claim procedure. A previously deducted amount may sometimes be recoverable from the overseas authority; HMRC does not itself pay that foreign refund.
When Is an Apostille or Foreign Form Necessary?
An overseas authority may ask for its own residence-certification form or for an apostille on a UK document. Submit any prescribed foreign form with the HMRC request where applicable. An apostille is required only when the overseas recipient requires legalisation. The Foreign, Commonwealth & Development Office (FCDO) decides whether a document qualifies for paper legalisation or an e-Apostille. A digital HMRC certificate is not automatically eligible for an e-Apostille; check the signature requirements and whether the foreign recipient accepts electronic legalisation.
A US Form W-8BEN-E is different: a non-US entity completes it for a US withholding agent. It is not an HMRC-issued residence certificate. Depending on the US payer’s rules, a UK company might need both forms.
Frequently Asked Questions About UK Residence Certificates
No. It identifies the incorporated entity. Corporate residence and treaty entitlement require a separate tax assessment.
No general indefinite validity should be assumed. HMRC certifies the relevant date or period, while the receiving authority decides when new evidence is needed.
Yes, if appropriately authorised. The company’s corporate residence and treaty eligibility must still be established
Usually not as a treaty resident under most UK DTAs. HMRC can confirm residence for qualifying partners, with limited treaty-specific exceptions.
No. The foreign tax authority decides claims under its own law and the relevant treaty.
Yes, if HMRC holds appropriate taxpayer consent authorising release to that representative.
Get Certificate of Residence Application Support From Tilly & Cooper
Tilly & Cooper Corporate Accountants can assist UK individuals and companies with tax records, HMRC correspondence and preparation of Certificate of Residence applications where authorised. For an initial review, provide the overseas country, income type, certification period, relevant UK tax reference, and any foreign authority form.
We can help identify missing records and prepare the information for submission. HMRC decides whether to issue the certificate; the overseas authority decides treaty relief.

